

I will get to the new concerns in a moment, but first let’s review how Tether works as well as the long-standing suspicions.
Please consider the Wall Street Journal April 12, 2018 article on the Mystery Behind Tether, the Crypto World’s Digital Dollar.
A fast-growing digital currency that claims to be backed by U.S. dollars has become a cornerstone of the volatile cryptocurrency market. The problem: There isn’t hard evidence the cash supporting it exists.
Unlike other cryptocurrencies that fluctuate wildly in value, one tether generally equals one dollar. This makes it a sort of digital-dollar substitute.
But Tether has never produced an audit showing it has the purported reserves. The company that controls tether maintains it has the reserves, yet it has never named the banks it uses to hold these funds, nor said where they are based and regulated.
Tether Ltd. marketed its cryptocurrency as a way to mediate the sector’s volatility—offering the safety of the dollar along with the speed and anonymity of a digital currency. The pitch worked. Tether’s market value has risen steadily over the past 18 months, to $2.4 billion from about $10 million at the beginning of 2017. That has made it a crucial link in the wider cryptocurrency market.
As a result, tether has become a key source of liquidity. At times this summer, tether has represented as much as 80% of bitcoin trading volume, according to research site CryptoCompare. When the year began, it accounted for about 10% of bitcoin trading volume. Nearly half of tether’s trading volume is among just a handful of tether-accepting exchanges, including some of the market’s largest.
Red Flags
Since the inception of Tether, there have been a huge number of red flags. The WSJ mentions a few of them.
- “There are a couple of forces in this market that if they failed, it would be catastrophic,” said Ding’An Fei, a managing partner at Ledger Capital, a digital asset investment firm in Beijing. “Tether is one of them.”
- Chainalysis also found tether trading is increasingly concentrated among smaller, more speculative digital currencies, a sign it is being used as a tool of “pump-and-dump” schemes, in which traders hype an asset, causing its price to rise, before dumping it for a profit.
- Tether trading in newer tokens such as EOS and NEO has risen to about 20% of overall tether volume, according to the report.
- The Securities and Exchange Commission recently singled out tether in its rejection of a proposed bitcoin-based ETF, citing studies that raised the possibility that the digital currency is being used to manipulate the bitcoin market.
Recent Plunge
With that backdrop out of the way, please consider the Tether Death Spiral by cryptocurrency trader Hans Hauge.
There are so many red flags around Tether, I don’t know where to start.
Bitcoin priced in Tether spiked to a premium of $1,000 above the market average on exchange Bitfinex, which owns Tether. The same thing that happened right before Mt. Gox collapsed. Tether traded as low as $0.86 on the Kraken exchange in the last 48 hours
First, Tether adds liquidity to the market, but it’s based on a lie. They’re supposed to have $2.5 billion in the bank, but do they? These funds are how they control the price of Tether, keeping it pegged to the US dollar. In other words, Tether should always be worth $1.00.
You notice that the Tether price starts to drop. It’s gone from $1.00 to $0.98 over the last couple days. People are getting nervous, and meanwhile, Bitcoin starts going up in price on Bitfinex. Then you get an email about “possible restrictions on withdrawals for some users.” In other words, you might not be able to get your money out. What do you do?
The answer you should have arrived at is just dump your Tether for Bitcoin!
Hauge notes that the price of Bitcoin to Tether spiked over $1,000 as people were unable to withdraw funds.
Banking Dilemma
Bitfinex lost their relationship with Wells Fargo back, but that’s old news now.
As they hop from bank to bank trying to stay afloat, it is already being reported that their relationship with HSBC is done after just about one week!
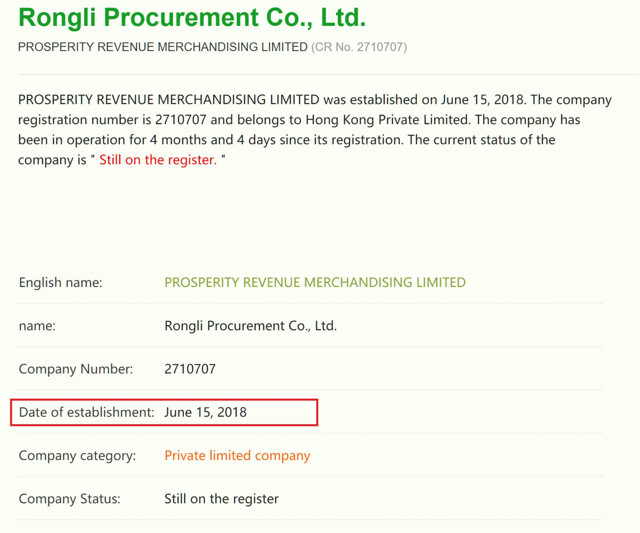
Apparently, a new bank has taken the stage from Hong Kong, called “PROSPERITY REVENUE MERCHANDISING LIMITED.” Does anyone care to bet on how long this relationship will last?
Oh, and this new bank… it’s four months old.
Rongli? Prosperity Revenue?

Head for the Hills
Hauge concludes, and I agree “If you own Tether, run for the hills.”
Is the money there? Who knows? I don’t. But long-standing suspicions suggest it isn’t.
Fraud Possibility
Here’s another possibility, even if the money is there:
Tether purposely creates these illiquid situations. Since it can time them, it can profit from them.
Dear Customers: You cannot do withdrawals. …
Ahead of such operations, Tether invests in Bitcoin knowing it will spike. Then Tether sells Bitcoin before sending the “all clear” signal.
That is just one of many possibilities. And of course the money might not be there at all and it is necessary for Tether to pull off these scheme to put back siphoned money.
Either way, and especially considering the WSJ’s suspicions, I have a bit of advice.
Get Out Now!
Mike “Mish” Shedlock


I’m more convinced than ever that precious metals and real estate are the safest widely held holds of value. Things that can’t be conjured out of thin air.
Thanks to CautiousObserver
You could take the converse view too – if you knew there wasn’t one dollar for every Tether you could short the heck out of it. Given the discount USDT/USD is a mere 4% it suggests that no-one is really that confident. 4% discount given the political risk seems very small as the entire banking system wants Tether dead and buried; and yet it continues – at least for now.
I could also make a cheeky comment along the lines of “oh now running a fractional reserve is a problem for people!” but I’d like to believe that Tether is honest but politically unviable.
Thanks to CautiousObserver
Tether is a great idea cursed by the inability to retain banking at the behest of the banking cabal. It’s use case exploded in volume last year – price arbitraging across exchanges. The problem they have is that retaining USD banking for them is impossible – hence the inability to audit – the instant the banks are known they are threatened with removal from Swift unless they terminate Tether accounts. People seem to delight/root for it’s failure – I don’t really understand why as this technology will free us from banker strangleholds. Doesn’t it scare the be-jesus out of you to consider that in a cashless world you can simply be censured/starved out of existence? In 2010 the USG did it best to terminate Wikileaks and only Bitcoin remained as the way to fund the unfundable. You all might root for a Brave New World/1984 – personally I don’t.
Nothing that renders you dependent on the “banking cabal” is a “great idea.”
Bitcoin was/is a great idea. Specifically because it endruns around the whole pile of undifferentiated rot, that constitutes absolutely every single minute facet of the Western “financial system.”
Blow up every bank, every bankster, every “financial center” and everyone with any link to any of them whatsoever, and Bitcoin is still Bitcoin. Well defined, distributed, not beholden to anyone and without any asymmetrically powerful participants that can coerce, debase nor otherwise steal from anyone else, just by virtue of arbitrary position or job title. No different from how any fair, just and functional system in free societies have to be organized.
While Bitcoin was/is a “great” idea, that doesn’t mean it can’t be made even greater. Experience has shown it to have some weaknesses that may need to be fixed before it can truly deliver on it’s initial promises of financial and transactional freedom. But cryptographic math is evolving at a good clip, and the engineering required to incorporate advances into a working product, will inevitably follow behind.
Then, the last requirement is a much more multipolar world. So that there will always be some places where you can spend your Bitcoin 2.0, even as the increasingly irrelevant privileged castes of the West, China and perhaps elsewhere does it’s best to “ban” it, in order to maintain unearned privilege for its own ruling Juntas.
I am surprised this is even up for discussion. Tether has broken the buck, badly. If there is actually US$1 securing each Tether then someone with inside knowledge would be exploiting the arbitrage by buying Tethers at a discount hand-over-fist until the price returns to $1. Since that is not happening, less than all of the money is there.
Based on what I have read, the main purpose of Tether is as an intermediary trading vehicle to synthetically get in and out of short term crypto trades more quickly and cheaply (because transitioning between crypto and US dollars is too difficult).
No thanks.
Excellent comment!
Someone finally gets it.
Guess what happens after the brief rise in btc pricing?
The coin flees to the real money exchanges ,
Then the real collapsicle starts.
They part of this story that sets off alarm bells for me is the bank switches. If Tether has $2.5 billion in the bank, just sitting there, every bank would want them as a customer.
Sorry but no. Every bank that has a Tether account is threatened – ditch them or be cut off from Swift. This is a fight for the bankers survival – they have an absolute monopoly on electronic money and you think they’re going to give that up without a fight?
yep, blame the used car buyer, not the used car salesman…
aka, blame the victim, not the con man…
that’s not to say some victims aren’t deserving but the comments below are ludicrous in their one-sidedness
There’s nothing ludicrous about NOT forcing prudent people willing and able to take care of themselves, to pay for a “system” with no other purpose than to bail out others who unwilling to do so.
If there is clear and obvious criminal fraud involved, say some guy with reserve account access just took the money to buy blow, it’s a regular criminal matter. But if crazy banking laws suddenly gets “interpreted” in such a way that reserves are frozen, or that the fees banks charge for taking the risk of holding the reserves bleed them out over time; that has nothing to do with fraud. Just business as usual.
Any dimbulb “investing” in something he knows nothing about how to make more valuable, is betting that value others create will be redistributed to him by some mechanism. If his bet pays off, he gains. If it doesn’t, he should lose. Not whine that the Junta should step in and rob others to make him whole.
In very old, large, broad, deep and established markets, with very entrenched rules, laws and traditions, one can reasonably expect all participants to have a common understanding of what means what. Leaving less room for claiming alternative interpretations are not fraudulent. But in something like this, where noone knows anything and everything’s up for grabs, what is even meant by “pegged” to the dollar? It’s just gobbledygook meant to sound “financy” and WallStreety to suckers. Anyone with half a brain and/or any kind of caution, just shies away.
Greedy imbeciles speculating in “imaginary” electronic ledger entries deserve all the misery they have coming to them.
Yup.
And that holds, no matter what happens to be the “asset” named in the electronic ledger….
Is there 1 dollar held safe somewhere for every 1 tether in circulation?
I am guessing most likely not.
This will further crash crypto currencies which have no value.
Somebody could take pink post-it notes and claim they are each units of currency and it would be the same as crypto currencies.
The only difference would be that pink post-it notes would not need lots of electricity (which costs actual dollars) to keep the currency operating.
With tulip bulbs one could always grow beautiful tulips…
There is no dollar held safe anywhere. That’s kind of the problem Bitcoin was trying to solve in the first place….. Duh!
No matter how big your supposed “reserves” are, and how “bluechip” and “audited” your bank is; all it takes is some ambulance chaser on the make, with a lawschool coke buddy turned judge, to have your reserves frozen pending some drummed up lawsuit that someone used your crypto to buy drugs, child porn, guns for scary muslim virgins and other fashionable hobgoblins.
Let me ask you a question. How much electricity, equipment, capital and human effort is used to maintain the ‘banking system’ as we know it? Sure Bitcoin is expensive in electricity terms – in fact that is the ledger defence against corruption as it makes it unviable for bad actors – but yet it’s a decimal point in expense compared to our current system. You just don’t see these costs.