
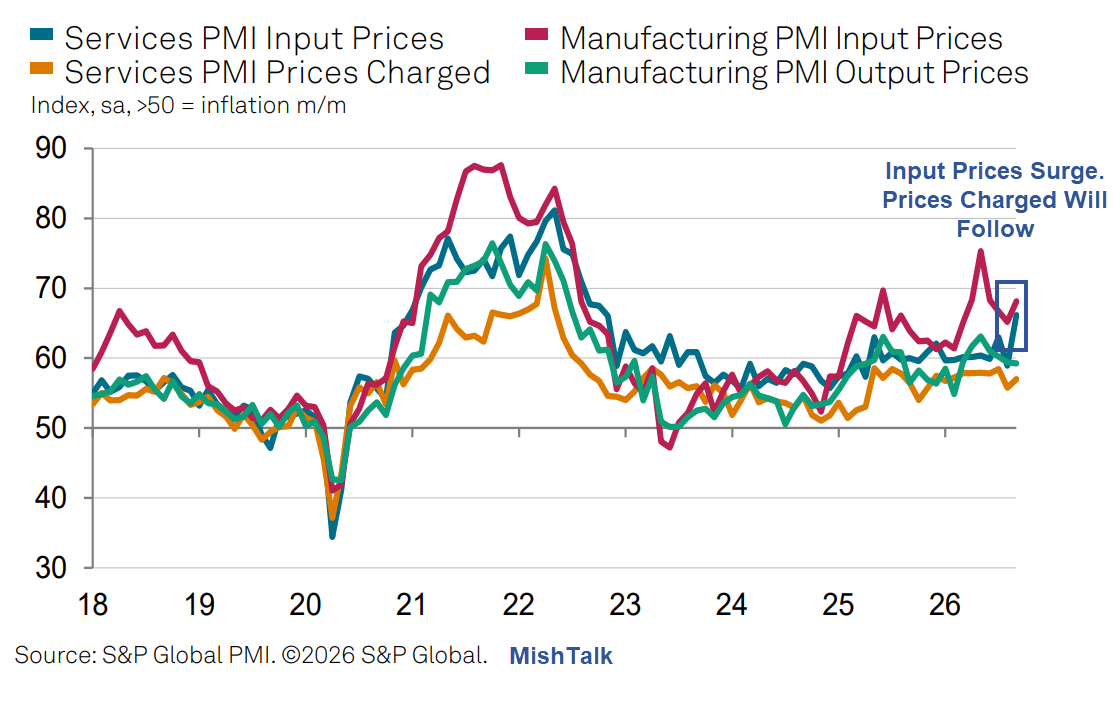
The S&P Services PMI is the trigger. Prices leap and shortages noted.
S&P Global US Flash PMI
Please consider the S&P Global US Flash PMI®
US business activity growth accelerated for a fourth successive month in September to reach the fastest rate for over five years. A further surge in service sector business activity was accompanied by a renewed improvement in manufacturing output growth. Employment also rose sharply, with jobs added at a pace not seen for over four years, as firms sought to meet rising demand. However, backlogs of work continued to rise at an increased rate and supply chain delays intensified, pointing to a lack of operating capacity which fed through to higher prices. Input costs meanwhile surged higher on the back of the recent spike in energy prices, adding to a worsening inflation picture.
Output and Demand
The headline flash S&P Global US PMI Composite Output Index rose from 56.0 in August to 58.4 in September, registering the fastest expansion since July 2021 and an acceleration of growth for a fourth successive month. Growth was driven by the service sector, which reported the steepest rise in output for over five years, but a welcome development in September was an accompanying acceleration of manufacturing output growth to the fastest since April 2022.
Price Pressures
Price pressures intensified in September. Average input costs measured across both goods and services surged higher, the overall rate of inflation hitting the highest since October 2022. The increase was blamed widely on higher fuel and transport costs, though wage pressures were also noted to have picked up in many cases. In manufacturing, high raw materials prices were also often linked to supply shortages; suppliers’ delivery times lengthened markedly again in September on average, with the incidence of supply chain delays the most widespread since July 2022. Input cost inflation in manufacturing nonetheless remained below the peaks seen earlier in the year, during the initial months of the war in the Middle East. Service sector input cost inflation hit the highest since November 2022. Selling price inflation also picked up in September, though was muted by competition in some instances, notably in the service sector. While above that seen in August, September’s overall selling price rise was below the rates seen between March and July.
Chris Williamson, Chief Business Economist at S&P Global Market Intelligence
Chris Williamson, Chief Business Economist at S&P Global Market Intelligence: “US business continues to boom, with output growing at the fastest rate for over five years in September. Historical comparisons suggest that the latest survey data point to annualized growth of around 5% with a 4% gain now signalled for the third quarter as a whole.
“To put the growth surge in context, barring the spike in demand following the opening up of the economy after the COVID-19 lockdowns, the latest improvement in business activity is the greatest recorded since early 2015. Business is clearly booming now in both manufacturing and services.
“However, this growth is being accompanied by some of the most severe supply chain bottlenecks seen in the near-two-decade survey history if the pandemic is excluded, with companies also reporting increasing problems finding suitable staff. Backlogs of work are consequently rising sharply.
While this accumulation of uncompleted orders bodes well for the further expansion of output and capacity in the coming months, it also indicates that companies are developing more pricing power, and hence is a worry for the inflation outlook.
“Firms’ input costs have meanwhile jumped in September at the steepest rate for four years, with fuel and transport costs spiking higher thanks to the rise in oil prices seen during the month, which will add further to the upward pressure on selling prices and inflation in the coming months.”
Bond Market Reaction

30-year and 10-year Yield Notes
- 30-year: 5.41 percent – the highest since July 27, 2024, over 22 years.
- 10-year: 5.13 percent – the highest since July 12, 2007, over 19 years.
When Does Yield Surge End?
- A recession severely reduces demand
- The AI boom ends
- The war in Iran ends and supply chains return to normal
It will take some combination of the above, perhaps all three.
Related Posts
September 22, 2026: The Average Supertanker Cost Is $1.2 Million per Day, Up from $29,900
High earnings for the biggest oil carriers spread to smaller vessels.
September 23, 2026: Energy Secretary Discusses a Voluntary Cap on Diesel Exports, Not a Ban
The idea is sure to annoy everyone for being too much or not enough.


30-year: 5.41 percent – the highest since July 27, 2024????? or should it be 2004 over 22 years.
Mish, this looks mostly driven by real yields as break evens are (surprisingly) well anchored, meaning inflation fears aren’t playing a part in the yield surge yet. It’s why it would may not be surprising to see 6-7% yields coming if bond investors actually become scared of inflation
All inflated dollars end up in the hands of the corporations with the highest ability to raise prices. Find them and buy them, and that money can end up in your pocket too.
rick santelli made a great point yesterday that supply chain problems are not most peoples concerns. we have a booming AI economy. whether it’s a fantasy or not, so far the construction and buildout is real as a heart attack. the booming economy of the early 1960s turned into stagflation by late 60s to early 80s. i might revert back to selling beer and soda on gas lines in nyc like i did as a teen
New record low on TLT. Time to buy-write another 100 shares. Dividend payout is usually on the 4th or 5th. If it goes down another 1% I will buy more, time to board the money cruise.
been short long term treasuries, too. i cannot wait for r/e to make sense again with cap rates in cities i know. the condo market is falling apart in a few locales i like. just a matter of time that one and 4 family houses make sense with very high cap rates. i waited 5 years in phoenix until i pounced in 2011 with cap rates in high teens and 20s. oakland and austin and cities in FL are looking wonderful with condos falling apart………hopes and prayers. my russian pals invested in kabul and baghdad when the USA started bombing after 9.11.01. both those towns were the biggest run up in market prices so far in 21st century. all those trillions of USD flooding those markets. i did not have the brains or balls of my russian oligarch and russian investment banker pals.
So good news in that interest rates are up so my income will go up.
Bad news in that my taxes will go up due to more income.
Who on earth would lend the government money for 30 years for 5.41%….a government unable to ever pay back the 40 billion it owes? Not me that’s for sure….try 15.41% and I might look twice.
$40 billion? $40 trillion.
$40B is chicken feed these days.
The government has never, ever had any intention of paying back its debt. That would be catastrophic economically. The government always, always rolls over its debt. That’s by design. The issue isn’t really the debt, its the annual deficit.
Another batch of amazing bickering comments about republican good/bad, democrats good/bad. Lol. It’s dejavu all over again.
The midterms are 40 days away and the voters, if allowed to vote, will decide the outcome and the question will be settled regardless of anyone’s personal views.
And no matter who wins, it’ll just be more of the same with marginal variations on who the crew is on the Trumptanic. You’ve got 849 more days with Captain Bligh.
Do worry, Trump, Walrus, GOP, and democrats will find a way to make things even worse.™
A credit downgrade is inevitable for the US.
40 trillion of debt and a lunatic at the helm will trigger that
i don’t think ratings agencies will take the risk until mein fuhrer is out of power. moody’s…….don’t want the university treatment……..
The ratings agencies have long been, if not foreverer, heavily in service of those being rated. This is even more the case for rating of US debt.
(I have no big opinion on the rating of US debt, just commenting that I have little trust that the rating agencies will rate in an accurate and timely manner on the risks of US debt.)
CORRECT
The last US credit downgrade was May 16th, 2025 – shortly after Trump took office. This was by Moodys from Aaa to Aa1 citing weak financial management from Washington. Things have deteriorated significantly since then.
While I agree that Trump has a heavy hand with the banks, they do control the banking system and can pull the rug out from Trump without batting an eye.
Stranger things have happened!
“Business is booming”? “Fastest expansion since 2021”?
What the hell are they measuring???
“Big companies” and “urban metro areas” as usual I’ll bet…because down on the ground, for the majority of people, prices are soaring, housing remains unaffordable, small business is doing it tough, multiple job holders abound and bankruptcies are rising.
Living standards are falling, especially when measured in terms of financial precariousness, savings rate and social discord.
You should get outside your own little village more – which sounds depressing.
GDP is currently estimated at 5.1% real growth rate at GDPNow.
And bankruptcies might be slightly higher than when the government was throwing out money for COVID, but compared to the last 20 years, bankruptcies are very low:
https://www.debt.org/bankruptcy/statistics/
That’s why statistics are collected and easily available online for free – to educate people that have very strong feelings about the ‘truth’ from their own ‘observations’
All of the Democrats and Canadians here have a vested interest in pushing this “terrible economy” narrative, either due to hatred for Trump, obsessive envy or the distaste for the level of sacrifice needed for true financial success.
All of the people I see are doing pretty well, and that ranges the gamut of working people through high-income, high net-worth. I don’t get where all of these people are that are complaining about how terrible things are.
Just look at the amount of downvotes this comment will get, and that will tell you everything.
“Looks good in my gated neighborhood!” is a sure election winner! I guess the looming midterm beatdown is all the Canadians illegally voting with democrats too? Oh, I can hear it now “polling isn’t real! I have the highest approval ratings ever actually!”
Cope after cope after cope, does it ever get old?
We know you want to be his Natalie, but a strong Businesswoman makes him feel threatened.
Nice straw man at the end
So what are planning to sacrifice?
You obviously don’t grocery shop.
Can you give a source for the GDP being that high? The real growth rate was, because that ain’t what I’m seeing from the BEA
https://www.bea.gov/news/2026/gdp-second-estimate-and-corporate-profits-2nd-quarter-2026
Mish’s site doesn’t like comments with more than one link. But GDPNow is referenced by Mish and many commenters here.
5.1% is an estimate for the upcoming 3rd quarter real GDP before BEA puts out the official number in 5 weeks: https://www.atlantafed.org/research-and-data/data/gdpnow
“5.1% is an estimate for the upcoming 3rd quarter real GDP before BEA puts out the official number in 5 weeks:”
Right, and how many weeks till the election? And you think the report will not be influenced in any way? Right!
“Living standards are falling, especially when measured in terms of financial precariousness, savings rate and social discord.”
Yes, but nobody of influence and authority cares. You think a farmer worries about whether his chickens are content and leading fulfilling lives as they are trucked to the slaughterhouse?
Th US dollar gapped up. There could be a currency crisis ahead.
The Viet Nam War started when interest rates were heading into the 60 years cycle. bottom. So a massive military operation should have started in 2015 when rates were near cycle lows and governments could afford to buy military equipment.
The Viet Nam War continued at least 12 years after the 60 year interest rate cycle bottomed in the early 1960’s. We’re 6 years past this 60 year cycle’s low. If rising interest rates were a problem, then the Viet Nam War should have lasted only 10 years instead of nearly 20. OR maybe interest rates should have prevented military action in Iran.
Interest rates didn’t have the same effect in this 60 year cycle as they did in the previous 60 year cycle, so maybe the causal relationship between interest rates and war needs to be reconsidered.
I sincerely hope this is a parody of how others are analyzing economics in today’s world
This is not a parody, but an example how financial markets are not simple causal systems.
40 years of lowering rates. 20 years of rising rates. the 60 year cycle. the cost of living when measured in calories expended per hour or day to be able to purchase calories per day………has been decreasing for centuries. the bond salesmen i grew up around in the late60s to 80s just drank in local bars. many friend’s lost their family businesses……..stuffhappens.
The big Viet Nam war buildup did not take place until 1965.
1/4 point hike wasn’t enough, and everyone knows it. If the Fed were were serious they would have done at least a 1/2 point hike. The Fed will continue to “fight” inflation from the rear for a long time now.
The Nattering Nabob’s “elephant tracks”.
Like Dr. William Barnett said (a former NSA Rocket Scientist), “the Fed should establish a “Bureau of Financial Statistics”.
IBDDs at the District Reserve Banks have been comingled with commercial bank IBDDs at their correspondent banks. GSEs, FMUs, Foreign Official balances, and certain eligible nonbanks (CLS Bank (FX settlement), DTC (Depository Trust Company), FICC (Fixed Income Clearing Corporation), NSCC (National Securities Clearing Corporation), OCC (Options Clearing Corporation), CME Clearing. I.e., almost every one that holds a “master account” at the FED.
I.e. it’s a universal plumbing/clearing stat.
An ample reserves regime indeed!
But like other metrics, e.g., currency, the dominant trend is the one to follow as they have similar rates-of-change.
Having studied reserves since 1979, there is usually a seasonal factor influencing volumes. Reserves typically decline until October 15. Thus, I sold everything 2 days ago in anticipation of a downswing (after the tax deadline).
Monetary flows’ propagation, are a mathematically robust sequence of numbers (sigma Σ), neither neutral nor opaque, which pre-determine macro-economic momentum (the → “arrow of time” or “directionally sensitive time-frequency de-compositions”).
Each and every year, the seasonal factor’s map (economic time series’ cyclical trend), or scientific proof, is demonstrated by the product of money flows, our means-of-payment money X’s its transaction’s velocity of circulation (the scientific method).
There are 6 seasonal, endogenous, economic inflection points each year.
(they may vary a little from year to year):
Pivot ↓ #1 3rd week in Jan.
Pivot ↑ #2 mid Mar.
Pivot ↓ #3 May 5,
Pivot ↑ #4 mid Jun.
Pivot ↓ #5 July 21,
Pivot ↑ #6 2-3 week in Oct.
These seasonal factors are pre-determined by the FRB-NY’s “trading desk” operations, executing the FOMC’s monetary policy directives (in the present case just reserve “smoothing” and “draining” operations, the oscillating inflows and outflows, the making and or receiving of correspondent and interbank payments by and large using their “free” excess reserve balances).
“I know of no model that shows a transmission from bank reserves to inflation” – DONALD KOHN – former Vice Chairman of the Board of Governors of the Federal Reserve System
“Reserves don’t even factor into my model, that’s not what causes inflation and not how the Fed stimulates the economy. It’s a side effect.” – LAURENCE MEYER – a Federal Reserve System governor from June 1996 to January 2002
Monetarism has never been tried.
Pre-2008
. As Dr. Richard G. Anderson (the world’s leading guru on bank reserves) wrote me:
“Spencer, this is an interesting idea. Since no one in the Fed tracks reserves…”
maybe how I denigrated Nassim Nicholas Taleb’s “Black Swan” theory 6 months in advance and within one day:
To: anderson@stls.frb.org
Subject: As the economy will shortly change, I wanted to show this to you again – forecast:
Date: Wed, 24 Mar 2010 17:22:50 -0500
Dr. Anderson:
It’s my discovery. Contrary to economic theory and Nobel Laureate Milton Friedman, monetary lags are not “long & variable”. The lags for monetary flows (MVt), i.e., the proxies for (1) real-growth, and for (2) inflation indices, are historically, always, fixed in length.
Assuming no quick countervailing stimulus:
2010
jan….. 0.54…. 0.25 top
feb….. 0.50…. 0.10
mar…. 0.54…. 0.08
apr….. 0.46…. 0.09 top
may…. 0.41…. 0.01 stocks fall
Should see shortly. Stock market makes a double top in Jan & Apr. Then real-output falls from (9) to (1) from Apr to May. Recent history indicates that this will be a marked, short, one month drop, in rate-of-change for real-output (-8). So stocks follow the economy down.
And:
flow5 Message #10 – 05/03/10 07:30 PM
The markets usually turn (pivot) on May 5th (+ or – 1 day).
I.e., the May 6th “flash crash”, viz., the second-largest intraday point swing (difference between intraday high and intraday low) up to that point, at 1,010.14 points.
“To put the growth surge in context, barring the spike in demand following the opening up of the economy after the COVID-19 lockdowns, the latest improvement in business activity is the greatest recorded since early 2015. Business is clearly booming now in both manufacturing and services.”
I can’t say I’ve heard of the S&P global pmi as being a market mover before. We have booming manufacturing but no employment growth in manufacturing?
Bonds were surging before the report came out so I attribute today’s rise to a failed 5 yr auction and oil price increases. Possible selling of treasuries by a pissed off world. Who really knows?
A diesel export ban will only increase the selling of treasuries as nations need more money for distillates.
Yes I stopped following PMI because ISM is more watched
What isn’t behind the increase? It’s easier to list things not currently teetering on the edge of oblivion. People can’t buy groceries, gas, or home goods, all the while the worst president in the nation’s history tells the whole world to eat cake. I think what comes next won’t be your average crash, that’s for certain.
“People can’t buy groceries, gas, or home goods…”
Sounds like someone needs to get a job!
And, this is false. We have a welfare system that will pay for literally everything a person needs, even if they only make minimum wage. But then, a lot of people don’t make very wise financial choices, do they (drugs, high-end gadgets, more car than they can afford, eating out, brand name clothing, entertainment, subscriptions)?
really? lol
I want to live in Businesswoman’s magical world. How much you wanna bet this is Jojo begging for attention under a different name? Either way, I’m loving this MAGA desperation and telling people to eat cake while their ship burns down.
She’s such a people pleaser, just wants everyone to be happy.
exactly, some people dont make very wise decisions.
like the truck drivers and farmers that voted for Trump. tell them how good the economy is, I am sure they will listen.
Weaponizing the dollar in war is not going to help sell treasuries. Nor in peaceful negotiations with allies.
The war might end … however I don’t see supply chains returning to normal … unless the reference is to some “new normal”
Chris Williamson’s quote seems to be describing a supply shock. From his comments, the “growth” seems to be concentrated in prices, not output.
Read much?
The first line of Williamson’s quote literally says ““US business continues to boom, with output growing at the fastest rate for over five years in September”
Don’t believe that? Go live in your own fantasy world. But you should not lie/fantasize about his belief/statement. It’s right there in black and white. Booming business and fast growing output preface everything else he says.
When Does Yield Surge End?
When there is severe recession US needs trillions and trillions of $ to revive its economy. China, EU, Japan, England definitely will not come to help. ( they have their own problems )
40+ trillions debt, 2 trillions budget deficit and multitrillion to revive the economy.
Yields will go through the roof.
If there is a severe recession here there will be a severe recession in all those countries too. They export too much stuff into the US to avoid the same fate.
The 60 year interest rate cycle tops in 2040.
Looks like Bessent badly sprained his ankle while doing the Treasury Twist!
This administration is hanging on by its fingernails, on all fronts: energy, inflation, credit costs, etc., to try desperately to keep things from really busting loose. We are on several edges right now, rushing toward us. A lot of numbers are running away from them (and us). The PR noise will keep the 30 percent bunker holdouts in place.
All this talk about rainbows and unicorns after the election is such bald-faced, insulting fantasy.
The only saving grace I can see is that this is coming home to roost in time for some corrective action to maybe arrest some of it by the election. but my money says a lot is already in the pipeline to spray out all over us, and we have no particular means to arrest it. So it will probably be another “hope and change” PR moment of relief without a lot to substantively change it, near term.
Dems still too much about revenge, next to not enough plans.
Couldn’t be due to trump’s policies and administration, as well as his excellent demeanor and character?
Absolutely not. What are you smoking?
Not really a believer in the “business is booming” narrative, especially when adjusted for real world inflation. I’ve never seen such divergences between GAAP and the garbage financials companies push out every quarter.
That’s scary, because it brings a whole different set of remembered fears. A crash is not the way we would want to arrest this inflation! The last one gave us real people falling off the edges, and MAGA.
Which last “Crash”, (that lasted at least 1 year)
1) Covid
2) GFC with Obama
3) Other(Credit Suisse for example/banks in California)
GFC occurred under Bush and Obama inherited the outcome. Not a fan of either but the wheels started falling off in summer of 2008. The stock market bottomed about 6 weeks into BO’s first term.
where did you study history GFC was all republican Bush and Cheny Obama inherited that royal fuckup. Its like I dont like the answer so I will make up a lie just like the molester and thief tell yourself its obamas fault sleep better knowing that you do not have to admit the truth a black man did not cause the GFC a white man did
Ok, GFC occurred under Bush and Obama inherited the outcome.
What was the remedy.
I did not vote for either, does that make you feel better.
I’m a bit confused. The Democrat posters here have been telling me that the economy is terrible, that we have a “food and energy” crisis on our hands, and that working people are getting completely stiffed by billionaires and trillionaires and quadrilionaires. Gas is so expensive that it still costs less than during the peak of Biden’s term. People are having to beg for leftover lobster and caviar in the streets!
And the blue states are carrying the entire load!
Yet companies are having trouble finding staff, there is enormous demand, and business production is at the fastest pace in 5 years.
With a bad economy like this, I wonder how you all will survive when there is an actual recession?
We’ll find out soon enough.
Those are good points. Having conservatives in charge of the nitty-gritty policies, along with some massive tax-cutting has been beneficial for the economy before, for instance during 2015-2019.
Talking to younger people, though, I don’t think they feel like times are booming.
Things like mortgage rates and healthcare, car payments, insurance, rent, and housing prices are making them feel locked out of prosperity.
Businesswoman is also conveniently forgetting COVID and acting like the economy just did that under Biden. Also “enormous demand” and “business production” seems to exist entirely on paper, as stated in Tax Haven’s comment. The real world doesn’t reflect these pie in the sky metrics with no explanation, but the GOP seems even more deadset than Biden’s admin on telling people it’s all fine. The difference is that there is no pandemic now, just one retard owning the consequences of his actions.
Well, I’ll believe someone on the internet named “Creamer” over Standard & Poors data, because…well, Creamer knows better! The same Creamer who apparently doesn’t have enough money for gas and groceries. He’s definitely got it all figured out!
Tax Haven’s comment was refuted.
And you keep calling me “Businesswoman.” Are you suggesting that this is an insult? Are you a misogynist? It wouldn’t surprise me if you were, given that most male democrats are hiding their poor treatment of women under the “male feminist” cover.
But you keep on. It makes me smile every time I see it!
“Refuted” by telling everyone what they see is wrong because what you see looks great and the stock market looks good? Genius! How was this data compiled? I guess I shouldn’t bother asking you. Nothing matters as long as the line goes up.
And on point two… why don’t you show me where the poor treatment of women is in the Democratic party. Allow me to counter with this gem from Mish’s recent post:
https://x.com/GOP__Ls/status/2101733203031552074
I’d really love to see the democrat congressman feeding kids his baby gravy. Since gas and food is magically cheaper for you, I’m sure you can find me this easily.
Smash that hide button and stop feeding trolls.
Usually when I do that the person is gone within a month. Thanks for the good idea!
yes Trump qudrupled the M1 in may of 2020 that is why Biden had inflation and yes Trump was president in 2020 for those who do not understand how the election cycle works the Democrats once again inherited a shit storm. they will again in 2028 and get blamed again because people do not understand there is always a delay between cause and effect
https://tradingeconomics.com/united-states/money-supply-m1
To be perfectly honest, I have never paid close to $4.39/gal during Biden’s administration here in central Florida. I paid that today. Most stations are priced at $4.29-$4.49/gal. Diesel is hanging around $6.09/gal.
You are lucky. Prices are up to $6.79 / gal for regular unleaded at my local stations here in central California. Enjoy what you’ve got.
Fair enough. Here is what AI had to say:
“Florida gasoline during Biden Administration’s 4 years:
Increase from low to peak~110%
The EIA’s weekly Florida series shows $2.329 on February 1, 2021, shortly after Biden took office, and a peak of $4.852 on June 13, 2022. AAA’s higher-frequency daily data puts Florida’s all-time statewide record at $4.8907 on June 13, 2022.
For some additional perspective, Florida was right around $2.30–$2.40 when Biden took office. AAA reported $2.30 on January 18, 2021, and $2.40 on January 24.
In summary:
Regular gasoline ranged from roughly $2.33 to $4.89 per gallon, with the peak occurring in June 2022. Annual averages ranged from about $2.88 in 2021 to $3.72 in 2022, before falling back to about $3.22 in 2024.”
So, Biden took the ultra-low gas prices of Trump’s first term and hiked them to over 110% halfway through his term. It was not all his fault, but that’s the folly of attributing every single thing that happens to every American as the President’s fault.
The inflation during FJB’s term had its roots largely in the response to COVID for the 10 months prior to F*** Joe Biden (FJB) taking office. Which was the last 10 months of the Narcissist’s term. FJB didn’t help matters by doing a 3rd COVID relief payment, but you can’t act like there isn’t a lag involved with inflation.
On a related note, the current spike in gas prices are entirely F*** Donald Trump (FDT)’s fault due to his illegal Iran war. So where are the stickers on the gas pumps of a smiling FDT pointing to the total price saying “I did that!”????
You can deny the existence of the K-shaped economy (or maybe you never learned what that means) – but if you look at how much wealth is in the stock market vs real estate, it does not take a genius to figure out the little guy is getting hosed and the rich are taking it all. You can attribute the nomenclature to democrats but you are only cheating your own intellect.
Lets also discuss the 5 year Treasury above 5%…
The “alchemy” of the US bond Market my be in Jeopardy…
And the dollar rallies, while gold gets clobbered because Uncle Schmuel’s debt is in the process of being re-rated to “junk status”.
You cannot make this stuff up.
Cleanest dirty shirt is the answer.
Filthy, dirty nonetheless.
LOL
You should look at some data before posting BS about ‘junk status’ debt
This graph shows the yield required for investors to fund the US debt since 1960. At least 50 years of that history shows rates at or above where they currently are:
https://www.macrotrends.net/2016/10-year-treasury-bond-rate-yield-chart
Was the US in ‘junk status’ that entire time? LOL
Italy 10-year government bond yield is 4.55%
Greece 10-year government bond yield is 4.36%.
Uncle Schmuel now pays more – considerably more than those 2 basket cases. It is well on its way to being “junk” whether you think so or not.
That’s the difference between me and you (and other similar commenters here). It’s not what I think or you think; it’s what the market thinks.
If you want to use your own personal Bam-Man definition of ‘junk status’ debt, I hope you have fun talking with yourself in the mirror.
But the market knows what ‘junk status’ is: https://www.investopedia.com/terms/j/junkbond.asp. And the US debt is nowhere close.
Don’t want to invest in it? That’s your prerogative. But you shouldn’t get upset when you’re called out on hysterical personal opinion you put forth on an economics blog.
About the surge in business activity. Samsung’s Texas chip plant which would cost up to 50 billion, didn’t have a single customer until Tesla stepped in. Maybe it will be profitable, or Tesla will buy it for pennies on the dollar.
“A further surge in service sector business activity was accompanied by a renewed improvement in manufacturing output growth.”
AI is getting better and better.
Have the military attack the bond markets?
(Don’t give Hegseth or the MAGA morons who post here any ideas, cat….)
Thank God a purely economic post.
CurveWatchers Anonymous back in the turret!
Looking at the chart, if the prices follow in the way they followed post covid/2021 they’re gonna need a bigger boat. The rates are starting at a much much higher level (FFR 4) than post covid, aka from ZERO!
Can you imagine what happens with rates needing to move much much higher on the short end? OOOOOOhh boy.
<insert song as Mish sometimes does> BTO – You Ain’t Seen Nothing Yet
I purposely did not mention anything political – yet it’s all political. the economy == politics
oikonomia
That’s a nice change. Regarding your last phrase, it reminds me of a cynical old lady in one of Ayn Rand’s novels who says, “All business is just dirty politics, and all politics is just dirty business.” You need to exercise more discrimination than that.
>the pedophile reads Rand
I’m running out of jokes for this.
It doesn’t suprise me one bit that you would dislike Rand or have no understanding of her message.
Collectivists are good at blaming everyone else, but never taking responsibility for anything.
We already had to hear how obsessed you are with kids’ genitals so I kind of had you pegged for a Rand lover to begin with. Nothing like the sound economic rambling from a woman who made her hubby pay to have sex with her!
I guess we’ll see soon in real time if politics = economics. Many have said here there will not be a Fed hike in October due to how it looks (politically) right before midterm elections, but with this hot (economic) data the odds are now 70%+ for a rate hike then.
Agreed, but that’s always the case. I just appreciated it and despite my kavetchcing sometimes I appreciate you authoring a post every day for like 25 years!
Thanks – At least one post every day Since March 2003
Because I switched sites 4 times, I am not sure if every post survived every moves