
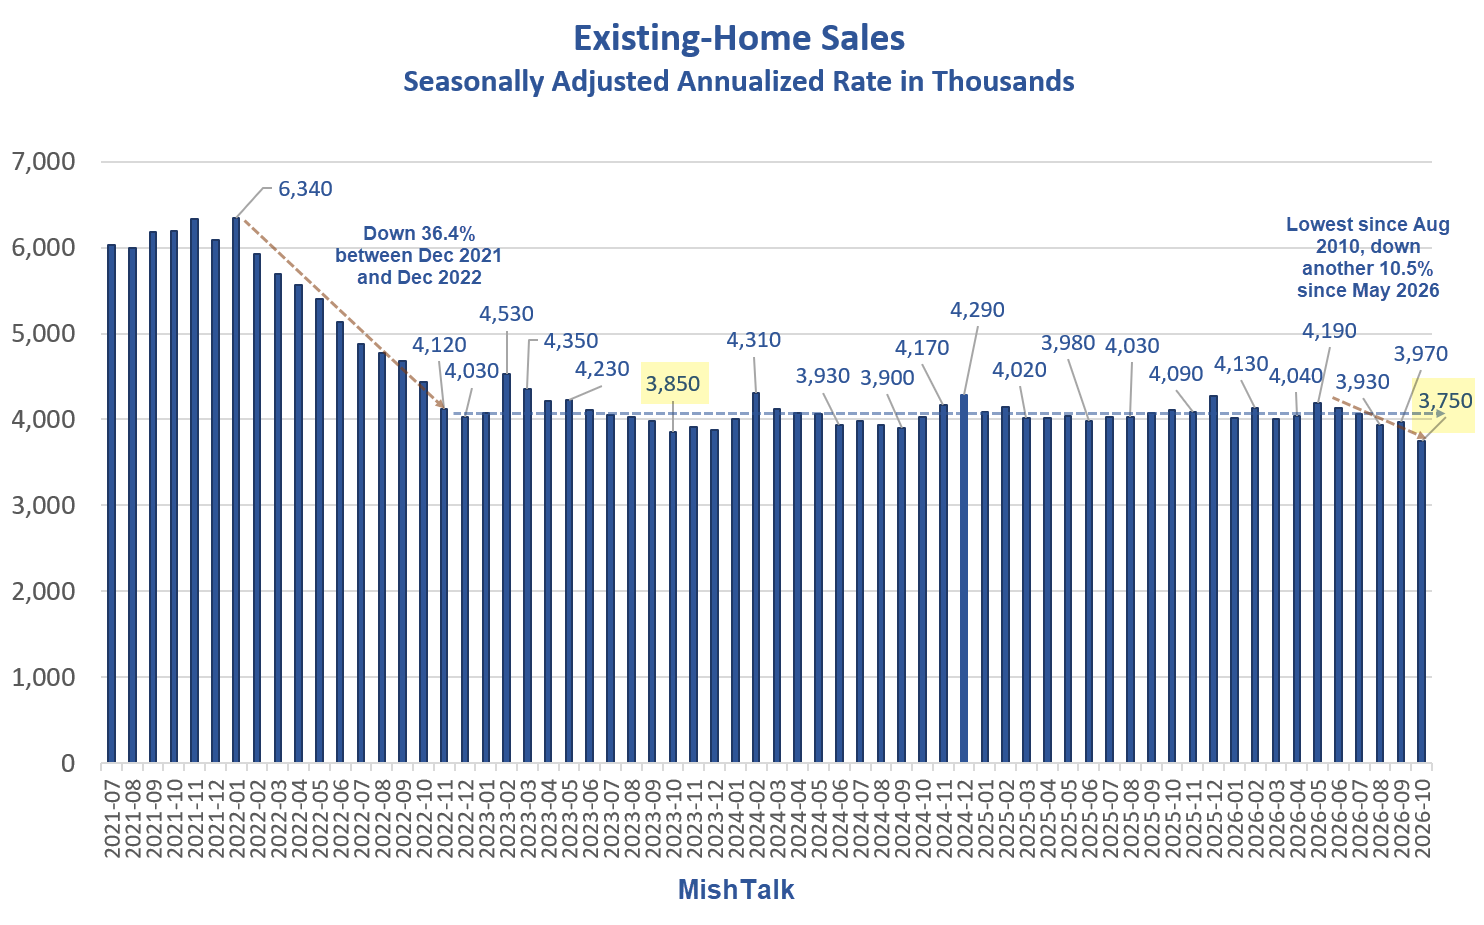
Existing-Home Sales are the lowest since August 2010.
The National Association of Realtors reports Existing-Home Sales Drop 5.5% in October
Existing-home sales decreased by 5.5% month-over-month and decreased by 8.8% year-over-year, according to the National Association of REALTORS® Existing-Home Sales report. The report provides the real estate ecosystem, including agents, homebuyers and sellers, with data on the level of home sales, price and inventory.
Month-over-month sales declined in the Midwest, South and West and held steady in the Northeast. Year-over-year sales declined in all four regions.
“Home buying is difficult when mortgage rates have climbed to their highest levels since 2000, aside from a single month in 2023. As a result, home sales fell to their lowest level since August 2010,” said NAR Chief Economist Lawrence Yun.
“Despite fewer transactions in October, the 88 million homeowners across the country are largely in a comfortable financial position due to sizable housing wealth accumulation. The number of distressed property sales remains historically low at only 2% of all transactions,” Yun said. “Based on the current underwhelming home sales pace at a time of consistent job growth, there could be sizable pent-up demand if mortgage rates decline.”
NAR Chief Cheerleader
Yun has been preaching versions of the above nonsense since January 2022. This is not a mortgage rate issue.
This is a price, quality, what you get for your money, interest rate, property tax, insurance, and overall inflation issue.
The NAR should change his title from chief economist to chief cheerleader.
Existing-Home Sales Month-Over-Month

Key October 2026 Statistics
- Month-Over-Month: Existing-home sales decreased 5.5% month-over-month million in September to a seasonally adjusted annualized rate of 3.75 million.
- Sales Year-Over-Year: Existing-home sales decreased 8.8%.
- Inventory Units: Unsold inventory increased 1.3% to 1.59 million units, equal to a 5.1-month supply.
- Inventory Supply: 4.8 months’ supply, unchanged from August and up from 4.5 months one year ago.
- Median existing-home price: The median existing-home sales price increased 0.4% to $416,700.
- Price Change From Year Ago: The median price increased 0.4% from $414,900 one year ago, marking the 40th consecutive month of year-over-year price increases.
- Market Time: The median time on market was 35 days, up from 33 days in September and 34 days in October 2025.
Existing-Home Sales Year-Over-Year

Existing Home Sales Supply

The NAR does not seasonally adjust much of its data as evidenced by the above chart.
Nonetheless, we can see rising supply over time. But rising supply has not helped sales.
Synopsis
- Real Income are falling
- Home prices are still rising in many areas but data lags
- Mortgage rates are back above 7 percent.
- Until two months ago, Yun ridiculously claimed affordability was improving.
Mortgage Rates

The current Mortgage News Daily rate is 7.30 percent.
MND is more accurate than the Freddie Mac data because it includes points and fees.
I use Freddie Mac data because I have a data download from the St. Louis Fed but not MND.
Existing-Home Sales vs Mortgage Rates

Over time, there have periods of strong and looses correlation between sales and mortgage rates
For example, sales went nowhere even as rates fell from 7.06 percent to 6.05 percent between April 2024 and April 2026, with Yun predicting stronger sales the whole way.
There is more to affordability than just rates.
But rates are over 7 percent again, and this time sales have responded.
Key Conclusions
- Home prices are too high, mortgage rates are too high, or both, for most people.
- For years, there was a pool of price-insensitive and mortgage rate insensitive buyers, around 4 million annualized, who were able and willing to buy regardless of point one.
Last month I commented “If we see a sustained decline in the stock market, a recession, or other economic shock, point two will not hold.”
Today I note the pool price-insensitive (and mortgage rate insensitive buyers) just gave out.
For whatever reason (perhaps the CPI or Fed rate hike fears, or no reason at all), existing home sales plunged to a 16-year low.
Sentiment can easily change on a dime, for no reason at all. Eventually, the pool of greater fools simply runs out.
Related Posts
October 7, 2026: Long-Term Bond Yields Surge to New 24-Year Highs
What happened to Bessent’s “I am the house” theory?
October 9, 2026: Consumer Sentiment Current Conditions Index Drop to Record Low
By political affiliation, sentiment declines the most for independents.
November 10, 2026: CPI Hotter than Expected Again. Expect a December Fed Rate Hike
This was the third consecutive bad month for CPI inflation.


The reason is Trump. It’s Trump turtles all the way down and inflation all the way up.
If I sold now, I would have a big capital gains tax to pay. So I am staying put for the time being. Calif. does not even have a reduced long term capital gains tax rate.
There are ways to avoid capital gains taxes on real estate.
https://blog.wealthstonegroup.com/insights/721-exchange-vs.-721-via-dst-whats-the-difference
I remember buying my house in 2011 (yes jackpot!) that my real estate agent had to work part time at Home Depot to pay the bills. And yesterday, my neighbor was telling me her daughter who is a RE agent in California is having a hard time with expenses and inflation.
Interest rates – how do they work?
The house across the street just sold for 3.5 million.
Mish, In your key conclusion you need to add the following point 3. Wages have not kept pace with any measure. 4. Serial bubble blowing by all central banks
I bought my first apartment on a salary multiple of 3.5 when I had been in employed for 2 years as a consulting engineer. About 2 years ago my son was looking to buy his first apartment so just as a table top exercise I went back to look at my first apartment and that apartment would have cost my son a multiple of 10 on his salary.
How high were your mortgage rates then?
Believe I saw where multifamily housing defaults are notably rising. Defaulted ones are more likely to see lower repricings w/ commensurate (incrementally) lower rents. (At least not higher as that net lower CF wasn’t working.) Which should incrementally make renting even more competitive Vs homeownership. Point is rental competition Vs homeownership will only presure homebuying more.
Effects on GDP:
Housing’s size in GDP (Q3 2026, latest quarter)
Little more color:
Housing’s effect on each quarter’s growth (the swing part)
Residential investment is the piece that moves the headline number, in percentage points of real GDP growth:
Q3 2026: −0.12 points — a drag on the 3.4% print; residential investment fell 3.3% annualizedQ2 2026: +0.10 pointsQ3 2025: −0.25 pointsIt’s fallen in six of the past eight quarters — Morningstar’s Caldwell put Q3’s drag at about a tenth of a point
A guesstimate would be it pulls -.30 to -.45 from GDP this Q.
I wonder if the NAR data include manufactured housing? Driving around, I am seeing what I believe may be increased units being placed on vacant lots and in designated communities.
Sellers haven’t yet fully come to terms with the fact that they missed the covid jackpot. Prices are reverting back to 2021 levels, and since they’ll briefly overcorrect, 2019 levels.
Myself, I am happy with this.
Home prices for distressed properties are really low right now, because no one wants a distressed property.
For all cash buyers who renovate and rent out, this is a bonanza. The only problem I have is with the time it takes to get one ready. I’d do as many as I could while the prices for distressed housing is low.
If you buy and fix up houses with cash and then refinance, it’s almost never been better here in Eastern NC.
This is why people can’t buy houses for themselves.
Capitalism is predatory by nature. Those that got in first prey on those that come later.
It is. Just saying this is a big factor to why people can’t get houses. With inflation rates going up, it will get harder.
On top of this predation, builders are 9lunwilling to build houses that can be sold. They still focus in $500K non starter homes
I like the idea that we are all benefiting from a “sizable wealth accumulation” until I realized that doesn’t pay the bills unless you HELOC.
With a 100% chance of a rate hike in December, January could be such a shit show that nothing gets done and Trump gets to blame the Democrats. But that’s nothing new, just renewed vigor.
except Trump will continue to say and do utterly stupid things and people will hate him even more over the next 24 months. And why would anyone want another repub in office again?