
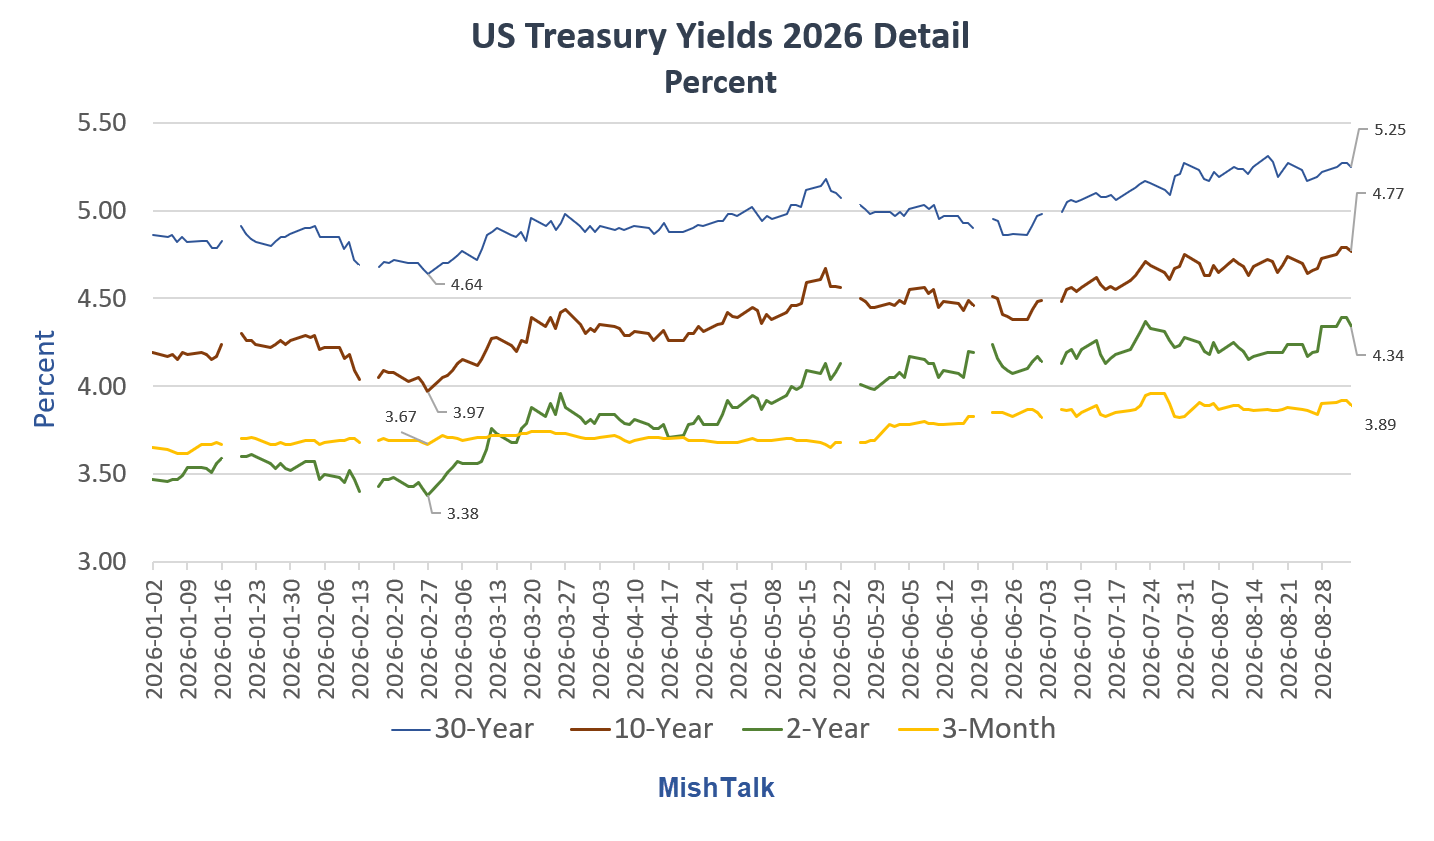
There are national and international forces pressuring yields. 
Change Since Start of War
- 3-Month: +0.22 Percentage Points to 3.89 Percent
- 2-Year: +0.96 Percentage Points to 4.34 Percent
- 10-Year: +0.80 Percentage Points to 4.77 Percent
- 30-Year: +0.61 Percentage Points to 5.25 Percent
Seven Forces Pressuring Yields
- The war in Iran: Oil, diesel, fertilizer and everything that passes through the strait is impacted
- US Budget Deficit: The deficit is growing and the administration wants more spending for the military, farm bailouts, and other priorities some related to the war in Iran.
- Debt: National debt passed the $40 trillion mark. Debt owned by the public is about $32 trillion. Interest on the debt projected to hit $1 trillion in Fiscal year 2026.
- Tariffs: Tariffs increase prices and slow growth. Trump’s trade war with Canada has heated up with negative consequeces.
- International: The US intervened in the Yen because Japan was about to dump US treasuries to buy the Yen. Curiously, Bessent wants Japan to hike rates and reduce debt (actions the US ought to be doing).
- AI-related Credit: A credit boom is fueling AI. Money supply is soaring.
- Treasury and Fed at Odds: The Fed and Treasury are fighting each other. Warsh wants a clean market signal and he wants to eliminate QE. However, Bessent is discussing unlimited Treasury actions to force down long-term yields. This impacts investor confidence.
Five Forces Impacting Diesel
- Harvesting Peak: August to November especially corn and soybeans
- Christmas Shipping: Peak annual trucking
- War in Iran: Reduced crude supplies
- War in Ukraine: Ukraine is bombing Russian refineries. Russia, normally a large diesel exporter, stopped diesel exports.
- Record Low Inventories: The Strategic Petroleum Reserve is at a record low.
AAA Fuel Prices

AAA fuel prices as of 11:00 PM September 7, 2026.
Twitter is littered with people wanting the Fed to stay on hold.
The unmistakable message from the bond market is the Fed is behind the curve and needs to hike.
The Fed should hike, and I believe they will hike unless the next CPI report is very tame. But that is highly doubtful.
Cleveland Fed Inflation Forecast
- The Cleveland Fed CPI forecast is +0.36 percent month-over-month with 3.43 percent year-over-year.
- The core CPI forecast is 0.20 percent month-over-month with 2.38 percent year-over-year.
- The more problematic numbers are PCE at 0.35 percent month-over-month and 3.80 percent year over year.
- The core PCE forecast is 0.27 percent month-over-month with 3.40 percent year-over-year.
None of these numbers call for a continued pause.
Only the CPI report will be published before the Fed meeting on September 16.
Inflation has been above the Fed’s target for 65 straight months with credit and stock market bubbles brewing too.
Yields at the long end are likely to surge if the Fed does not hike.
The Blame Game Rotation
- Covid
- The war in Ukraine
- Tariffs
- The war in Iran
It’s Always Something
Right now that “something” is Trump.
This “soon too end something” has gone on for 65 months with the Fed and White House (both parties) offering excuses why it’s transitory.
It’s been transitory alright, but to higher inflation, AI-related credit bubbles, reinsurance bubbles, and stock market bubbles.
Something Will Break
Something will break, guaranteed. And the Fed will get the blame, except for the wrong reason.
The problems are loose credit, easy money, and bubbles, not the hike that is sure to get the blame when something goes wrong.
Related Posts
September 5, 2026: China Halts Some Rare Earth Element Shipments to the US
- Ahead of Xi’s meeting with Trump, China holds back rare earth shipments.
September 6, 2026: Democrats Propose Free Money for Stay at Home Parents. Are You For It?
Sorry, I meant to say this socialistic proposal is by Republicans, not AOC.
September 7, 2026: Hello Farmers, Diesel New Record Near $6, Labor Day Gasoline Record Too
A week ago we were looking for $5.80 Diesel, now $6.00 is in sight.
Political Realities May Force the Fed to Hike in September
On August 31, I commented Political Realities May Force the Fed to Hike in September
It will be a stretch for the Fed to pause for many reasons, not just the CPI.
Click for Details.


3. Debt: National debt passed the $40 trillion mark. Debt owned by the public is about $32 trillion. Interest on the debt projected to hit $1 trillion in Fiscal year 2026. Your words Mish.
The Public Debt is in fact owed by the US government, to non-US government people and organizations.
The even more important Intragovernmental Holdings (IH) debt, that are not even mentioned by you, are actually owed to US workers and various pension funds and government contingency funds that the Government spends now, rather accumulates, for future use.
Your wording confuses what is a liability and what is an asset. That means when the (SS) Social Security Admin says they have enough money to last another 10 years, and they are lying. They actually ran out of money i.e. cash, 20 years ago. So the government must borrow cash (monthly) to pay retirement benefits.
This play on words is used by politicians (and now you) to deceive voters into thinking we have another ten years to fix the SS (Social Security) crash.
So what has happened is that the Government barrows cash (by selling US bonds) every month to fund (SS). The same treatment is true for Military and Civil Service pensions. Also. down at the bottom of this list of liabilities there are smaller items that we take for granted, like the $ 118 Billon skimmed out of the Highway Construction Trust Fund and (are you ready for this) The $81 Billion spent from F.D.I.C. fund needed to protect our Bank Accounts.
All these items are a higher priority the Debt Held by the Public and you ignored them.
References: U.S. National Debt Clock : Real Time
Q&A: Gross Debt Versus Debt Held by the Public-Thu, 08/20/2026 – 12:00 | Committee for a Responsible Federal Budget
I don’t confuse anything and you quoted me accurately
Do a search for why economists focus on debt owned by the public.
As for SS – I suspect it runs a out a few months earlier than projected.
Hi, What’s valuble information used buy some economists is missleading to 95% of Americans. If you believe that the Social Security Trust Fund has any value (other than unfunded IOUs) you have been Gaslighted.
P.S. Where is Sharron Watkins when you really need her?
I would make it “Six Forces Impacting Disel”.
IMHO #6 is a top one:
#6.) Record Diesel Exports
W/o #6 things could be, likely would be, quite different.
Oops, I can’t count and thus null and void!
Should say EIGHTH factor!
“Hike”? What is a hike going to do to rate-sensitive sectors of the already doddering economy?
And how is a rate hike supposed to bring down oil prices?
I still maintain they should CUT. But they will hold until after the GOP loses races in the midterms.
I wouldn’t say that they SHOULD cut. But, I will say that with all these bubbles that they have created, they are forced to cut and do QE and YCC and what not, just to keep it going for a little while longer.
No, this time is different. The Austrian business cycle is bunk. The ratio of demand deposits to time deposits has tripled. That precludes forced QE.
The rate-of-change in monetary flows, the volume and velocity of our means-of-payment money supply, the proxy for R-gDp, has now peaked and is falling rapidly.
6/1/2026 ….. 0.241
7/1/2026 ….. 0.247 peak
8/1/2026 ….. 0.142
9/1/2026 ….. 0.056
The question is does “Quantity leads and velocity follows” Cit. Dying of Money -By Jens O. Parson
AD = M*Vt = GDP
But velocity is moot:
Large Time Deposits, All Commercial Banks (LTDACBM027NBOG) | FRED | St. Louis Fed
I.e., the economic items are not synchronous.
I agree. “When interbank demand deposits fall, settlement liquidity tightens.
When settlement liquidity tightens, the liquidity premium rises (short-term liquidity premia rise, interest rate spreads rise). When the liquidity premium rises, interest rates rise — even if the Fed does nothing.”
IBDDs have fallen by 331449b since July 3rd 2025. This is pushing up interest rates in the short-run. So far, we have avoided the “Minsky Moment”
10-Year Treasury Constant Maturity Minus 3-Month Treasury Constant Maturity (T10Y3M) | FRED | St. Louis Fed
Are you advocating we should not be accountable for our past malfeasance wrt fiscal responsibility? Not going to happen as bond holders are going to want their money back when they realize their capital is in jeopardy or they are going to want compensation for the additional risk. That is what makes rate sensitive sectors rate sensitive.
If the fed cuts, they will need to print and buy federal debt to enforce the lower than market level rate. Printing leads to inflation that makes rate sensitive sectors even more rate sensitive. The fed shenanigans have reached their endpoint, this is why congress has to cut spending below revenue or the problem gets worse, not better. Unfortunately, rate cutting now reinforces the downward spiral. We are entering tough times that are the consequence of years of fiscal irresponsibility, the timeline for repair is going to be measured in years, there will be no Fed magic.
Trump wants zero percent rates. Trump will get zero percent rates (so his buddies can continue to buy up America with no-interest money, as they have been doing since 2006 — and they like it.) It is amusing that a dictator-wanna-be didnt realize that the REAL dictators on Iran would have no trouble torturing and killing as many people as necessary to hold onto power and thwart Trump. Does the man ever look in the mirror? Also, dictators dont care about inflation. Whatever it takes to bring the rates back to zero …
The greatest force on the bond market investor mood. It has been characterized structurally and temporally by R.N Elliott and J.M Hurst, respectively. The nominal 54 year interest rate cycle, which has been running averaging 60 +/-1 years for the past 230 years bottomed in 2020, and is expected to top in 2040 +/-1 year.
So my question for naysayers is, how can the 60 year interest cycle be so precise even though each cycle had different leaders, technology, and events?
We all use different market strategies. If this Elliott wave theory has been “precisely” correct for 1/4 of a millennium, I assume all its acolytes are the richest of the rich now, knowing exactly how to invest and prosper.
Congrats
The Elliott Wave theory works in retrospect.
Higher oil prices also pressure heavy importer Japan to raise rates. The consequent relative repatriation of Yen then also tends to push up US interest rates.
If oil goes high enough, it could trigger a nasty Yen carry trade unwind. Which will seriously affect investment asset prices all over the place.
i think the trade war tariffs, on top of the idiotic iranian war……..on top of mountain of debt and inflation will end up being as bad as the great depression.
Emanual Cleaver in a conference call with his constituents told them the Democrats will end all the tariffs Trump has imposed after the elections.
What happens when all the empty office buildings, that were re-financed in 2020-21 at generational lows in rates, have their debt mature in the next 2 years?
REIT-wrecks, ahoy!
Same thing that always happens when re-financing occurs in interest-rate transition periods.
One person/company takes a beating (or goes bankrupt), and another gets the ‘deal of a lifetime’
The physical buildings are still there for use; only the ownership changes.
TO your point, there have been stories about buildings sold for huge losses.
Unless they can do the better alternative: “Extend and pretend” – if cash flow and Creditor can align.
One month T Bills have already been pricing in a hike regardless what the Fed does. 3.75%. So who cares what the Fed does, except for Optics?
Because the Fed directly controls the overnight federal funds rate, interest on reserve balances (of commercial banks), and the reverse repo rate (which financial institutions like money market fund managers use).
You’re talking about what individuals do with extra cash when they want to loan short-term to the US Treasury.
The Fed – and its direct connections to banks and financial institutions – affect a lot of loan rates, and that will affect the economy considerably
20ish yr’s ago I ran a Bil+ in MoneyMarket funds. Watched Fed changes, et al. My education was that:
The Fed discourages borrowing from them at “The Window”. Also b/e that implies a sicker bank who can’t otherwise get [even collaterialized] borrowing – which is most always the case. THEY can precisely control this; and Reserve Rates.Commerical Paper (CP) & “Disco’s” (Treasury related Disccount Notes) <18 mo’s Mty’s go into Money Market Funds. THESE the Fed does not explicitly control.But I assure you, they move in Price/Yield like the Fed does!. And if need be the Fed can add and subtract securities from these overnight/ultra-short term markets.I went through all this to point out The Fed does NOT explicitly have “its direct connections to banks and financial institutions”; but rather deals in +/- Liquidty changes [and implicit direcctives pretty much without using a stick] to effect changes in Rates [ergo Fed Funds] and Reserves. Therein, CP, being a ‘close substitute’ [sans the requisite credit aspect] for Disco’s pretty much trade in [basis point] lockstep. Thus Money Market Account interest rates move along in this range. [Thanks to the DIDMCA Act and the resulting Disintermediation creating this; but precipitating the earlier S&L Crisis beforehand.]
If the Fed “discouraged” borrowing from the discount window (in your example), by definition they did not “precisely control this”.
I said the Fed “affects” (not dictates) a lot of loan rates. But the Fed DOES have direct connections to banks and financial institutions. It directly supervises and regulates financial institutions. And those institutions directly keep money and loans with the Fed.
And if you were in the biz 20 years ago, you quit working before the Fed dropped its minimum reserve requirements on banks. So its rates affect banks even more now (via opportunity costs).
Yes, but post GFC they must pass CCAR and Dodd-Frank. Which have Basel I, then II, and now Level III Risk based Capital Requirements and I’ve worked in banking on this.
You act like banks can do anything they want. NO. They can not depend on The Fed’s Overnight Window w/o risking Regulators on the doorstep – and seisure.
Do you know what “Fed Funds” consist of? INTERBANK [mostly overnight] LENDING. Banks can not do that w/o adequate capital ratios to convinve other banks to do it. It is NOT a given.
Done. Pass
Yeah, the time frame of the FED’s horizon became 24 hours rather than 24 months in 1965.
Great list but Trump messing with the elections will cause total chaos. That may be the pin that pops the bubble.
Do worry, Trump, Walrus, GOP, and democrats will find a way to make things even worse.™
“Something will break, guaranteed.”
A lopsided economy, invested in a “gee whiz” innovation, with structures of financial engineering erected all around it. A record high stock market. Expensive military misadventures abroad. A spike in fuel prices. An awakening left. A president who says it is all going fine.
Welcome to 2008.
Mish mentions distributing blame when things go boom,
I think there will also be more disorder being distributed this time because of depleted tool kits: Fed/national debt running against constraints, and a middle-to-lower classes post-2008 more bitter and for some, more fragile. What was Obama and Occupy Wall Street may become a much more confrontational situation. Domestic bitterness deepened (hence Trump). We had urban riots as recently as 2020.
I think this is all going to make my retirement prospects very interesting. I sat very cautiously on real estate assuming it would be enough. The 2008 mess lasted years.
Meanwhile, China reaches across the seas. Some big stuff out there will shift around.
Excellent comment. 2-star Mishelin award. I fully expect violence to explode when all of this crashes. There is already a substantial increase in thefts, robberies and more as more people get desperate. And we haven’t really seen inflation hit hard yet, that’s still coming: food inflation, insurance inflation, energy inflation, etc.
There will be predators and there will be prey. Which one will you guys be?
perhaps it will be YOU. i hope NOT. i neve wish harm to anyone. i’ve been mugged a bunch, beat up, and also shot at on streets of usa, in my short life. 70s 80s nyc was colorful. i’d be careful. i hope you are not some travelling amerikan who gets tarred and feathered as a scape goat.
Your resume shouts, “prey!”
Thanks for playing.
de nada, amigo. you are no doubt the smartest person that ever lived.
If you think you’re the predator, MPO45v2, you’re probably the prey.
There’s ALWAYS a bigger fish.
My survival will depend on three elements:
Ag, Au and Pb.
Gotta go now and look for my carry permit.
You mean the now Department of Fubar?
I’m still predicting that Trump declares martial law after the election
The Fed and Warsh face a Trump administration that consists by now exclusively of morons, people like Trump who have no clue about monetary policy, and phonies, people like Bessent who are knowledgeable but can keep their jobs only if they agree with the morons. Warsh will have to decide sooner or later whether he wants to keep playing a de facto phony or not. Ironically, if Warsh now raises interest rates and Trump calls him a traitor, Warsh‘s and the Fed’s credibility in the markets would skyrocket.
Great insight
The Federal Reserve ultimately looks out for the Federal Reserve.
Well, Trump has asked for cuts all the way to zero percent. So, if Warsh doesn’t cut, or even if he cuts 25 bp, he can project himself to be “tough”.
They are all useless bastards. All of them.
For something really to break, one or more big banks would have to have a credit event. Something along the lines of heavy speculative investments in federal or corporate bonds where the declining values force mass sales to make their own debt payments.You would also need the Fed to stand back and let the bank(s) fail, as opposed to stepping in and buying those bad investments at par. What are the chances?
> “the Fed to stand back and let the bank(s) fail”
Won’t happen. society cracks apart that day. This takes us back not merely to 2008, but to the 1930s. Perish the thought. Because that means other things break all over the world.
Yes. There is no way they’re going to let a bank fail…..and the banks know it.
I do not disagree that a big bank failure could be the pin for the huge everything bubble we are in, but I do not think it alone could cause a collapse. We had serious problems after 911 and it was a tragedy, but it also was the destruction of a symbol of US national pride and stature in the world, namely world trade and the NYSE. I would think an attack on another national symbol such as Cape Canaveral Space installation, would trigger a huge decline in citizens buying consumer items they do not really need. That would be a serious hit to private GDP contribution and sales tax revenue hitting state and local governments very hard.
I agree with you that a bank failure won’t cause a collapse in the general economy
But I’m also not de-investing to wait for an attack on a national symbol either.
I am not waiting for an attack on a national symbol either, it was just an example.
The FED can rescue a few banks, but I don’t think it can rescue the system.
I agree, with the national debt and deficit, Fed’s monetary policy is basically impotent as anything of major consequence is inflationary or destructive to the country’s ability to service its debt.
Quite a few big banks went belly-up quickly in 2023 due to speculative bond investments (don’t you remember the hand-wringing here and elsewhere about the ‘bailout’?.
For the past three years since then, real GDP and the stock market has continued to increase.
It will take more than a bank failing (even a big one) to make this economy turn completely downward.
What is a reinsurance bubble?
This is one example:
“The Brookmont Catastrophic Bond ETF (Ticker: ILS) is a pioneering financial product launched on April 1, 2025, on the NYSE Arca. It is designed as the first-ever exchange-traded fund to democratize retail access to catastrophe bonds (Cat bonds) and alternative insurance-linked securities (ILS).”
I think you missed the 8th force which is a highly dysfunctional congress and senate and perhaps a ninth force which is the uncertainty of the midterms. Will this be a free and fair election? If the democrats get control should we expect more income taxes and higher government spending? Certainly we should expect even greater dysfunction. As a minimum there will be two more years of BS of some sort likely an impeachment effort and a lot of vetoes.
Crude up $2.50 overnight and Canadian tariffs about to rise bi-laterally.
What could go wrong?
You know what’s going to go right? Profits for those positioned in oil stocks or options.
Trump rarely suffers the consequences of his stupidity. Other than the Epstein class the rest of us do.
warsh ain’t hiking coming around the far turn and into the home stretch of the midterm epstein midterms. i’d bet a cheeseburger with fries and a shake, on that.
Two more meetings before the midterms. If he is going to hike he needs to do it now. Otherwise he will be hiking shortly before the mid terms and Trump will go ballistic. I think he has to hike as the market is hiking without him and he can’t become so disconnected with the market that he can’t sell treasuries without deep discounts.
Can’t the “foreign buyer” banksters buy more UST? Maybe they’ll buy more if Bessent guarantees to buy them back at par whenever the banksters want out, as long as the banksters send a % to the correct bank accounts.
his vote counts the same as everyone else.
NOT really. or how the history of it goes. but technically, yea.