
It’s more nowhere for now, but a big caution ahead.
The National Association of Realtors reports Existing-Home Sales Decline 2.0 Percent in August.
“Mortgage rates and home sales move in opposite directions, so it’s not surprising to see a mild dip in home buying activity due to high mortgage rates,” said NAR Chief Economist Lawrence Yun. “Still, home prices are rising, and existing home sales are actually up 1.6% year-to-date through the first eight months of the year. Homebuying demand, despite higher interest rates, is no doubt being supported by rising wages, which grew 3.1% in August, along with 643,000 net new jobs added since the start of the year. Job creation and wage growth typically drive housing demand.”
“The number of months it would take to exhaust the total inventory at the current sales pace has grown to 4.9 months’ supply—its highest level in over ten years. The ample supply of homes for sale on the market is giving homebuyers better opportunities to negotiate,” Yun added.
Yun Nonsense
Year-over-year sales are down, so Yun resorts to a year-to-date number to say something positive.
As for “better opportunities to negotiate”, what a crock. But you really have to love the absurd “Homebuying demand, despite higher interest rates, is no doubt being supported by rising wages”.
If rising wages supported housing, there would be more home buying.
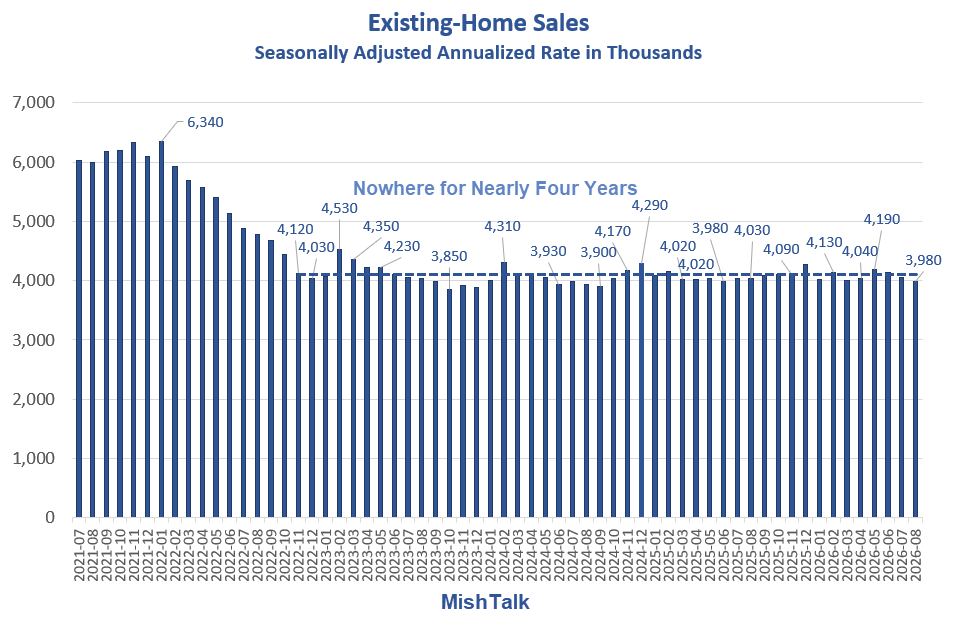
The lead chart says it will be four years of nowhere in two more months.
Existing-Home Sales Month-Over-Month

Changes have been essentially trendless for years.
Key August 2026 Statistics
- Month-Over-Month: 2.0 percent decrease in existing-home sales month-over-month.
- Sales Year-Over-Year: 1.2% decrease in existing-home sales year-over-year to a seasonally adjusted annual rate of 3.98 million. The last time sales activity fell below 4.0 million was in June 2025.
- Inventory Units: 1.62 million units, up 3.2 percent from July and up 5.9 percent from August 2025. This was the first time since November 2019 that inventory exceeded 1.6 million units.
- Inventory Supply: 4.9-month supply of unsold inventory, up from 4.6 months in July and 4.6 months in August 2025.
- Median existing-home price: $429,100: Median existing-home price for all housing types
- Price Change From Year Ago: 1.6% increase from one year ago ($422,400)—the 38th consecutive month of year-over-year price increases.
- Market Time: 31 days: Median time on market for properties, up from 29 days last month, unchanged from 31 days in August 2025
Truly Nonsensical NAR Measures of Affordability
- The Housing Affordability Index registered at 104.7, up from 101.2 a year ago.
- Northeast +0.5%
- Midwest +1.7%
- South +4.5%
- West +5.9%
If homes were more affordable, more homes would be selling.
Existing-Home Sales Year-Over-Year

Existing Home Sales Supply

The NAR does not seasonally adjust much of its data as evidenced by the above chart.
Nonetheless, we can see rising supply over time. But rising supply has not helped sales.
Existing-Home Sales vs Mortgage Rates

There are sometime jumps in sales when rates drop. However, there has not been any lasting traction.
Sales have basically gone nowhere even as rates fell from 7.62 percent to 6.05 percent.
But rates have risen again. The current Mortgage News Daily rate is 7.07 percent.
MND is more accurate than the Freddie Mac data in my chart because it includes points and fees. I use Freddie Mac data because I have a download from the St. Louis Fed.
Three Key Conclusions
- Home prices are too high, mortgage rates are too high, or both, for most people.
- There is a pool of price-insensitive buyers, around 4 million annualized, who are able and willing to buy regardless of point one.
- If we see a sustained decline in the stock market, a recession, or other economic shock, point two will not hold.
Point 3 above is my big caution.
Synopsis
- Real Income falling
- Home prices rising
- Mortgage rates rising
- Yun claims affordability is improving
Related Posts
September 9, 2026: Has Job Growth Accelerated or Should We Be Skeptical? What Does QCEW Suggest?
- Here are 8 charts and tables to discuss.
September 9, 2026: 10-Year Yield Hits Multi-Year High, Long Bond Tops 5.3 Percent, Oil Surges
It’s not a good day in the markets, Here’s a recap.
September 10, 2026: Bond Yields Surge, Gasoline Up 5 Cents, Fed Interest Rate Hike Odds Jump
Hello Mr. President, still want to hand out $1.3 trillion in free bribe money?


Four straight years of absolutely flat sales, even if seasonally adjusted, screams “managed” unit sales volumes. It’s as if a “whatever it takes” situation is being managed under the covers to prevent any sort of cascading shock from ever developing.
Asset valuation prices are driven from the appraisal of loan collateral, and loanable funds, which depends upon Gresham’s law: “a statement of the least cost “principle of substitution” as applied to money: that a commodity (or service) will be devoted to those uses which are the most profitable (most widely viewed as promising), that a statement of the principle of substitution: “the bad money drives out good”.
10yr real interest rates became negative during QE up until the FDIC initially activated monetary savings in 2013 (reducing FDIC insurance from unlimited in transactions deposits to $250,000).
Not even the small rise in real rates was sufficient to counter the funds channeled into residential real estate (as bondholders were driven into higher values in inflation protected hard assets).
On 10/9/2008 interest on reserves was initially set at .75%, then raised to 1.15% on 10/23/2008, then on 10/29/2008 lowered to .65%, then on 11/6/2008 raised to 1.00%, then on 12/6/2008 lowered to .25% until 12/17/15.
During this entire period between the initial introduction of the IOR until 10/30/15 6mo T-Bills remained below interest on reserves.
The IOR induced credit crunches beginning on 10/9/2008. Banks could earn more by holding reserves at the Fed than by holding T‑bills. Banks could arbitrage in overnight funding markets by borrowing at rates below the IOER rate and maintaining the proceeds in their reserve account at the Federal Reserve. Demand for T‑bills (bank investment) was artificially suppressed. The Fed effectively “sterilized” its QE balance sheet. It reduced gross national product. It raised real estate valuations.
The US Golden Age in Capitalism was driven by high real rates of interest (incentivizing high household and business savings) and low rates of inflation. The US Golden Age in capitalism was driven in 2/3 by velocity and 1/3 money (the exact opposite of today’s monetary policy). I.e., today’s economy is being run in reverse.
Lawrence Yun has been the NAR chief economist since I began reading this blog 25 years ago. Is there proof he actually exists? Does he have the job for life?
The taco economy continues to move in the same direction as has been the case since the deranged clown took over.
And remember everyone’s favorite NAR quote: “It’s never been a better time to buy/sell/whatever-no-matter-what” a home!
More like a mantra.
But we were told that as soon as Trump took office all those job stealing, expensive home buying, welfare benefit taking immigrants would be deported and housing would become practically free for everyone. What’s going on?
We were also told interest rates would go back to zero ushering in a new golden age. What’s going on?
We were also told no more wars. What’s going on?
We were told so many deals for farmers would happen, they’d be filthy rich but instead they are just filthy. What’s going on?
We were also told Epstein files would be released. What’s going on?
Does anyone know what’s going on?
I am starting to worry that Trump, Walrus, GOP, and democrats will find a way to make things even worse.™
Take off those shit-colored glasses, gloomy Gus… it’s a golden age out here!
You forgot the /s required for the down voters so that they don’t need to think.
There will always be people who can buy in cash. If the market starts to fail, there will slightly fewer of them. And if the market goes up, there will be slightly more of them.
In both cases, there will be fewer people who can afford a house, especially in the “mortgage only” class. If the market goes up, the competition for more houses will drive prices beyond many. If the market goes down, there just are not as many in a cash only position.
i’ve been a cash buyer of 2 to 5 family houses for decades. much better deals to be had. r/e just requires patience. stock trading is much more fun and easier. i like both.
The cash helps. Most of us are lacking.
NYT rent vs buy calculator tells the real story. Only thing that makes buying even remotely close to worth it monetarily is infinite aggressive appreciation, and I see nothing that will sustain that.
Now if one wants to build your little castle and play house, and it’s worth the extra spend, that’s a different matter entirely. I view it as just one more physical possession that empty people use to build an identity to present to the other empty people… hence the popularity. Most people are empty.
That same emptiness is behind most of the stupid crap we do as a species.
exactly correct. watch “the century of self” documentary by adam curtiss. free on youtube
I believe it’s less likely to get kicked out of the place you bought. Security has a price. Just my 2 cents.
There are plenty of other places to live.
what if we just let Donald Epstein and the MICC apply Artificial Intelligence to the problem of mortgages and home prices ? would they just burn them all down and we can have a reset and do over, as a human species. go back to africa and begin walking upright. i’d imagine the first human primates who used fire for cooking were thought to be the witches and devils of our kind. get Elmo Musk and Donald Epstein on this problem asap.
The AI says bulldozer that suburb and build a nuclear powered data center on it. For the good of mankind.
If AI determines the value of any given humans by what they contribute to the world, a lot of people are destined to have their housing replaced by chicken coops
sounds like a great plan. do it in my backyard. NIMBY
Point Three is your big caution. I would say that you are correct on all three points and those points lead to falling prices for homes. In truth, though, I’ve thought this for about three years already, and it hasn’t happened, but, I think it’s inevitable.
You see it on the low end already. There are people that NEED to sell their house, and after it hasn’t sold for some period of time, they drop the price and get it sold. Then, that becomes the new set of comps, and, prices in the area begin to fall to that level.
Next it will be the next higher up level of home (in my area the “low end” is under $300,000, the next level would be the $300k-$500k), and then slowly the entire market will reset.
I’m not talking about massive price drops, but, my guess would be in the 10 – 25 percent on a price per square foot basis (my back of the envelope guess anyway)
depends where. some places will get crushed more than they have. austin and oakland come to mind. my old craftsman bungalow hood in historic downtown of phoenix went down about 75% from top to bottom back in the last panic two decades ago. was great for buyers like me in 2011 and 2012. cap rates about 20%
Wolf posts on this every month or so. Austin is now essentially at the bottom given its current prices represent 3% increase from 2000 (26 years of matching inflation). Many other markets are also back to being fair valued based on 2000 prices like Austin.
Oakland still has a ways to go yet based on 2000 prices as do many other markets. His posts are worth looking at if you are trying to figure out which markets are priced right vs too high.
Not familiar with Wolf, and can’t seem to find his analysis searching, do you have a link Tim?
his blog is wolfstreet.com . mish has referenced him.
Thanks yippee
de nada old sport
correct. i follow wolf too. my properties i owned in oakland are worth less today than when i bought them in 2015. glad i sold years ago. the towns i know and have invested in r/e across the usa do seem to line up accurately with what Wolf posts. his blog is good. he doesn’t like any challenges to his thinking. no big deal. i’ve been going to college since 1978 and find many academics and wealthy men possess that small thinking too. i know i don’t know many things and assume i’m wrong. and embrace being wrong. it makes for a good trading career. face reality.
Mortgage rates continue to be historically low and real wages are actually keeping up with inflation, Mish. What planet are you getting your data from? On the other hand, who wants to give up their 2 5/8 % rate they got 5 yrs ago. Little Johnny (25-40 years olds in US) is living with mommy and daddy 50% of the time-why buy a house when you can live off your parents?
meanwhile: Federal Agents Are Secretly Monitoring Americans’ Financial Transactions So Cops Can Arrest People They Find Suspicious
https://futurism.com/future-society/federal-agents-monitoring-financial-transactions
democracy works. the people want to snoop on their neighbors and themselves. democracy works. those are fighting words in a democracy that has voted for decades to be a worldwide warmongering asshole empire.
and: Trump’s Gift to the Money Launderers: Treasury isn’t merely shutting down an anti-corruption database. It’s deleting the data so future investigators can’t use it. Catherine Rampell on the destroyed institutional capacity that let biological, social, and financial parasites flourish — a golden age for white-collar crime
https://www.thebulwark.com/p/trumps-gift-to-the-money-launderers-database-treasury
Looks like it’s time to make a career pivot to white collar crime, as a matter of survival. These ghouls will take EVERYTHING and sneer at us for starving.
It ain’t just Trump. It’s been estimated that 10% of uk gdp is dirty money, much of it laundered in plain sight.
The median price of a home is over 400k, where exactly is little Johnny coming up with that grandpa Joe? Is his Trump account going to pay for it? Will it be from his new job doing construction that we got rid of the illegals for that pays 40k a year? You seem like a smart guy, give us an answer!
Mortgage rates are only “historically low” compared to the late 70’s and 80’s. They’re higher than in the 60’s, 50’s and 40’s – and most of the 21st century.
Do tell where you live. But be warned, I’ll be joining you there.